The YFG Approved standard
Every broker we introduce is YFG Approved
Over two hours one on one with our founder, then their references, reviews, licence and accreditations checked. Here is the standard in full, so you can hold us to it.
What are you borrowing for?
- Buy a homeFirst home, next home or investment
- RefinanceCheck your rate against the market
- Business financeCash flow, growth or a new premises
- Car loanNew, used, electric or novated
- Equipment financeVehicles, machinery and tools
- Personal loanRenovation or debt consolidation
Free, with no obligation. Your answers go to one YFG Approved broker, not a list.
Six checks before a broker hears from a single borrower. Approval can be lost.
What the two hours are for
Andy sits with every broker himself, one on one, for over two hours. He is checking three things, in his words.
They understand their profession
A broker carries real responsibility for a family’s biggest debt. We make sure they know it.
They know how to write loans
Knowing the lenders is not enough. They need to know how to put a loan together properly.
They get people what they need
Not what pays the broker best, and not what is quickest. What the borrower actually needs.
Brokers earn the YFG approval. They can lose it.
A licence is the minimum, not the standard. Before a broker hears from a single borrower they pass six checks, and they have to keep passing them. It takes us hours per broker, and it’s meant to.
Paying us doesn’t buy approval. A broker who fails a check doesn’t get enquiries at any price.
The YFG Approved standard: six checks
Two hours with the founder
Andy spends over two hours with every broker: how they work, how they write loans and how they look after people. If they can’t show they know their profession, it ends there.
References checked
We speak to people who have worked with them, so we hear how they operate when nobody is selling.
Reviews read
We read what their clients say about them in public, the hard reviews as well as the good ones.
Licence and accreditations
Their Australian Credit Licence or credit representative number, looked up on ASIC’s register, membership of AFCA (the free complaints scheme) and their accreditations.
Held to our rules
Your enquiry goes to them alone, not to a list, and they call within one business day, already knowing your answers.
Answerable to you
If a broker doesn’t call, doesn’t explain your options or doesn’t treat you well, tell us. We follow up every report, and a broker who falls short loses their YFG approval.
“We check every broker. I spend over two hours with each one to make sure they understand their profession, know how to write loans and get people what they need.”Andy McMaster, founder
Licensed brokers who meet our criteria pay Your Finance Guide a partnership fee to receive enquiries from this site. The fee is paid by the broker, not by you, and is not added to your loan. Read our Credit Guide.
Why we check the broker before the rate
The rate on the sign is rarely the rate people pay, and a licence is only the start. Two numbers, from the people who keep them.
between the banks’ standard variable rate and what new borrowers actually pay.
The standard rate is 8.77%. The average new variable home loan is 6.23%. On a $600,000 loan over 30 years, that gap is about $1,040 a month. The price of a home loan is negotiated, and it depends on who is asking.
people banned or disqualified by ASIC from credit work.
176 of those bans are still in force. Rules catch people after the damage is done, which is why a licence is where our checks start, not where they end.
So we check the broker first.
Sources: Reserve Bank of Australia, statistical tables F5 (September 2026) and F6 (August 2026). ASIC Banned and Disqualified Persons register (credit), data.gov.au, 19 October 2026. Checked 21 October 2026.
Three steps, and you sign nothing until you’re sure.
Your answers, in a few quick questions
What you’re borrowing for and a few basics. No credit check at this step, no account.
One YFG Approved broker
A broker who has passed every check calls within one business day, already knowing your answers. You can pick a time that suits you.
You decide
They compare lenders on their panel and explain why an option suits you. There is no obligation, and if anything feels off, tell us.
Free, with no obligation to go ahead.
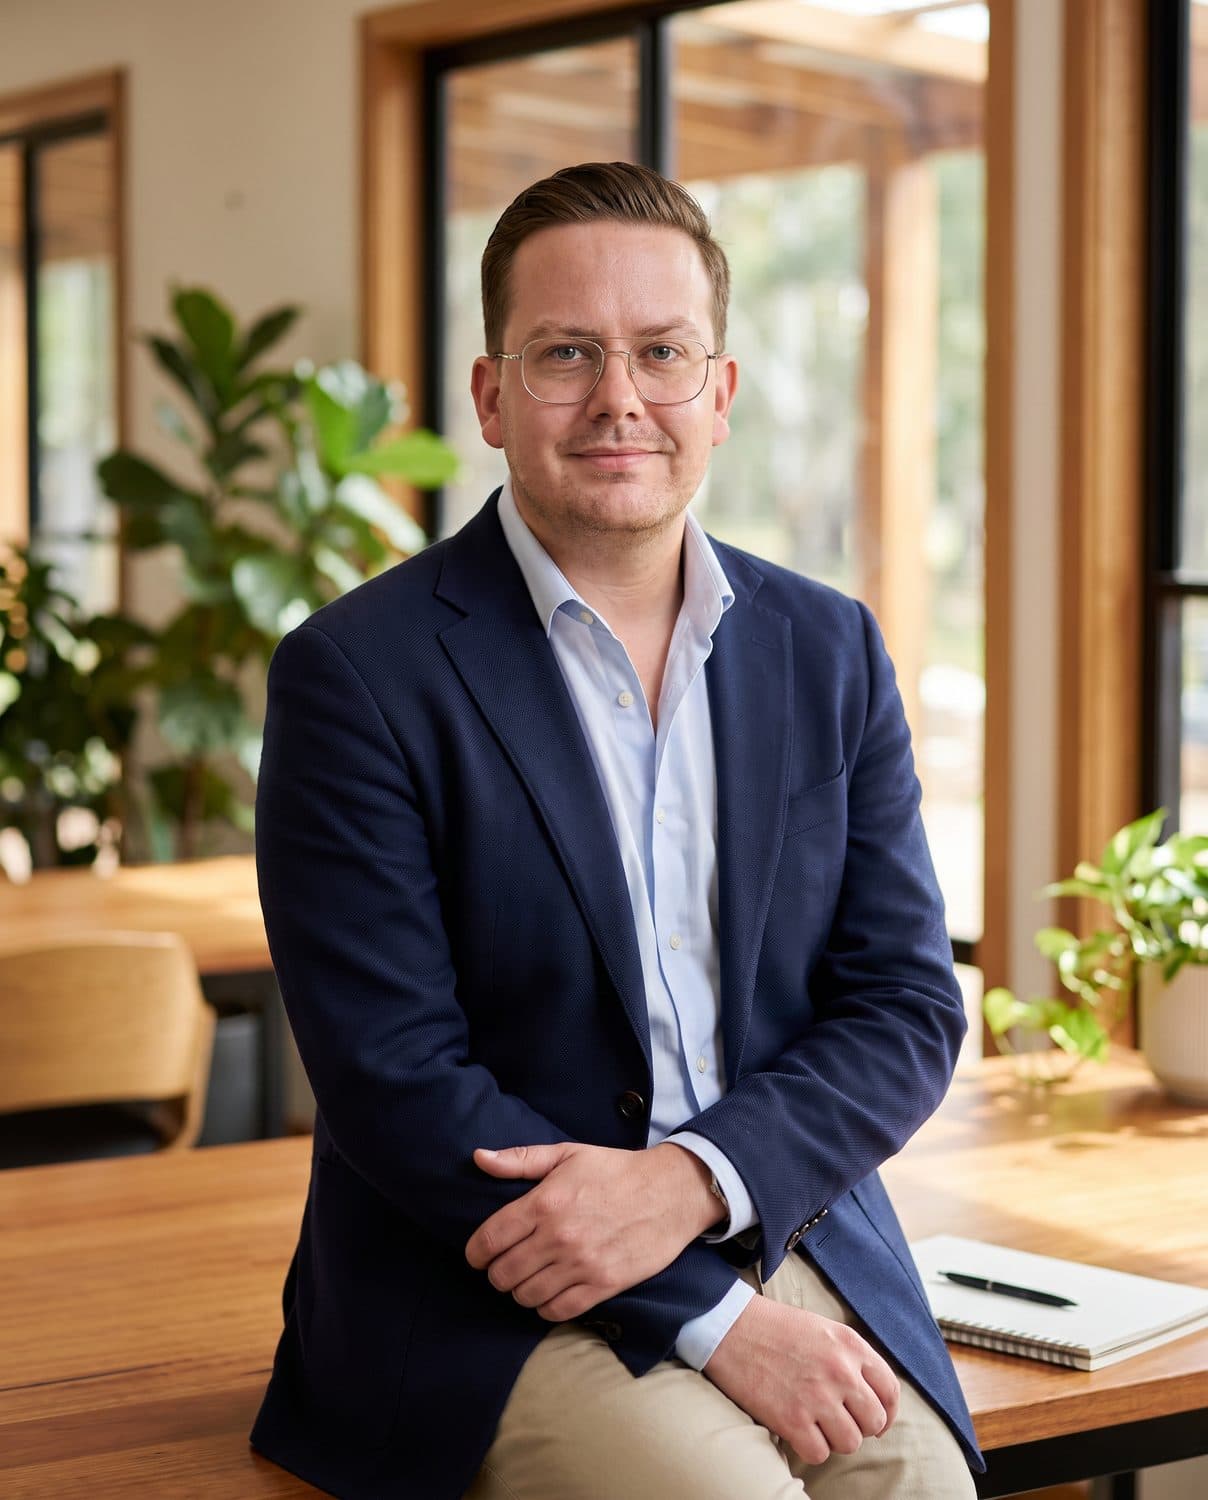
Andy McMaster, founder. More than a decade in the property industry, advising buyers and investors. Every broker here has spent over two hours with him first.
“I got tired of seeing people get ripped off.”
So I built Your Finance Guide to be the benchmark.
I’ve spent more than a decade in the property industry, advising buyers and investors. Over that time I got tired of seeing people get ripped off: by lenders who let loyal customers drift onto worse rates, and by the people who were meant to be looking after them.
A home loan is make or break for a family trying to set themselves up. The right one gives you room to get ahead. The wrong one costs you for decades, and most people never find out.
I built Your Finance Guide to be a real benchmark in an industry that needs one. Before a broker hears from a single borrower, I spend over two hours with them, making sure they know their profession, know how to write loans and get people what they need. Then we check their references, their reviews and their accreditations.
It takes a lot of time. It’s meant to. If a broker doesn’t meet the standard, they don’t get your enquiry, and if they stop meeting it, they lose their place.
We don’t sell loans. We vet the people who do.
- More than a decade in the property industry
- Over two hours with every broker, one on one
- A founder you can name, not a call centre
What we do, and what we don’t
We check brokers. We don’t lend.
Your Finance Guide is not a lender or a broker, and we don’t give credit advice. The broker you speak with is licensed to do that, and works out which loans suit you.
One broker, not a list
Your answers go to one YFG Approved broker who works with loans like yours, not to a list of brokers or lenders.
How we are paid
Licensed brokers who meet our criteria pay Your Finance Guide a partnership fee to receive enquiries from this site. The fee is paid by the broker, not by you, and is not added to your loan. Brokers are usually also paid a commission by the lender when a loan settles, so ask how they are paid. Read our Credit Guide.
Seven questions to ask any broker
Ours included. Take them to every broker you speak to, before you sign anything.
How many lenders are on your panel, and how many did you compare for me?
Two or three is not a comparison.
Why is this loan in my best interests? Can I have that in writing?
By law a mortgage broker has to work that out. Asking for it is fair.
How are you paid on this loan, and would another lender pay you differently?
Commission is normal. Being told about it is the test.
What is the comparison rate, and which fees make the difference?
What does leaving my current lender cost: discharge fees, break costs or a cashback clawback?
What happens to the rate when any honeymoon or fixed period ends?
Does the new loan keep what I use, like an offset account or redraw?
If they hesitate, ask why.
A good broker answers all seven without hesitating. Every YFG Approved broker expects to be asked.
Questions about YFG Approved
Who decides whether a broker is approved?
Andy McMaster, our founder, after spending over two hours with the broker and after we have checked their references, client reviews, accreditations and licence. Approval is looked at again whenever a borrower tells us something went wrong.
Can a broker pay to be approved?
No. Approved brokers pay a partnership fee to receive enquiries, but the fee comes after the checks, not instead of them. A broker who fails a check does not get enquiries, and one who falls short later loses their approval.
What happens if my broker falls short?
Tell us. Reply to your confirmation email, which comes to us and not the broker, or email us any time. If a broker did not call, did not explain your options or did not treat you well, we follow it up, and a broker who falls short loses their YFG approval.
Does YFG Approved cover car, business and personal loans too?
Yes. Every broker we introduce goes through the same standard, whatever the loan. Only mortgage brokers are bound by the legal best interests duty, so for other loans ask the broker to explain why the option they recommend suits you.
Does approval mean you recommend a particular loan?
No. Your Finance Guide does not give credit advice or recommend loans. YFG Approved is about the broker: who they are, how they work and how they treat people. The broker works out which loans suit you, and you decide whether to go ahead.
Are you a broker?
We only work with licensed brokers who pass the standard. If you want to be one of them, start with an application, and expect the two hours with Andy.
Check the broker. Then check the rate.
Free, and nothing to sign until you’re sure.
What every match includes
- One YFG Approved broker, not a list
- A call within one business day, at a time you can pick
- Options compared across the broker’s lender panel
- No cost to you, and no obligation
- Your answers, so the first call starts with your options
- Someone to tell if anything goes wrong: us
Your Finance Guide is a finance education publisher. We are not a credit provider, broker, or lender, we do not hold an Australian Credit Licence, and we do not provide credit assistance. When you request a quote, your enquiry goes to a licensed broker who meets our criteria and compares rates from a panel of Australian lenders. Full details, including the licence we work in conjunction with, are in our Credit Guide. Credit Guide