Chattel Mortgage Calculator
Work out your chattel mortgage repayments in seconds, then see what lenders could actually offer your business.
For vehicles used more than half the time for business.
Your rate depends on your business, the vehicle and the lender.
$236.21 a week
- Amount financed
- $50,000
- Total interest
- $11,416
- Balloon at the end
- $0
- Total repaid
- $61,416
On your numbers, every 1% off the rate saves about $1,420 over the loan.
That’s an estimate. Want the real number?
Lenders price every business differently. Answer a few questions and a licensed broker finds the lenders that fit yours.
Estimate only. This is not a quote or an offer of credit. It assumes the rate shown, no fees, and repayments at the end of each period. Your actual rate and repayments depend on the lender’s assessment.
Every 1% off the rate is worth about $1,420 to you
That’s what a broker comparing lenders is for.
Why check your options with us
One broker, not ten phone calls
Your details go to one vetted broker only. No call centre, and no list of lenders chasing you.
Lenders compared for you
Your broker compares lenders from the 50+ on our broker partners’ panels, including specialists for new ABNs and low doc.
ABN holders welcome
Sole traders, companies and trusts. New ABNs and low doc options considered.
No credit check to start
Seeing your options doesn’t touch your credit file. Nothing goes to a lender until you say go.
The check is free
Brokers who meet our criteria pay us a partnership fee, not you. Your broker explains any fees before you sign anything.
A real person, fast
A licensed broker calls you within 24 hours to talk through your options.
How it works
Answer a few questions
About 60 seconds, and your numbers come with you.
A licensed broker compares lenders
They line up the lenders that suit your business and the vehicle.
They call you with options
You decide. Nothing goes to a lender until you say go.
Your rate isn’t one number
ABN age, GST registration, credit history, deposit and the vehicle’s age all move it. A broker knows which lenders suit your mix.
Your broker compares lenders like...

Lenders your broker can compare include Prospa, Moula, OnDeck, Judo Bank, Angle Finance, Latitude, Capify, Earlypay, Plenti, Liberty, Macquarie, Westpac, ANZ.
Examples of lenders on the partner broker’s panel. Which ones are open to you depends on your circumstances, and no lender can be promised.
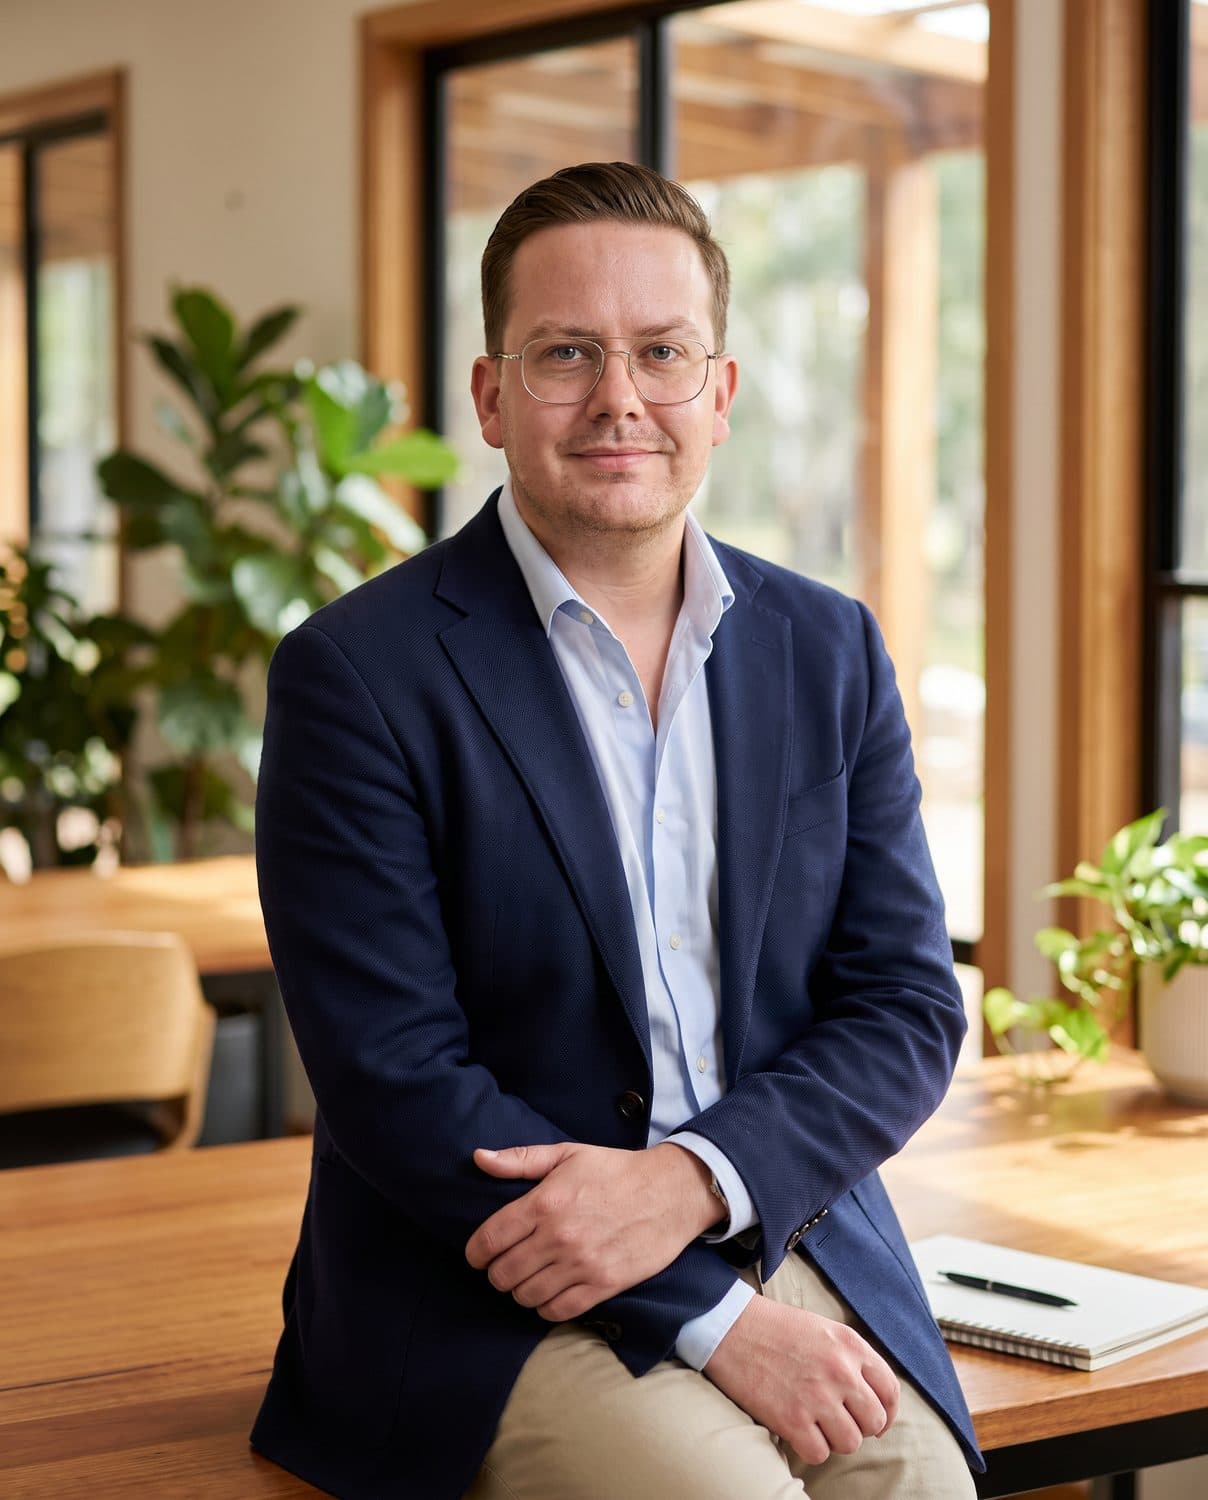
“I got tired of seeing people get ripped off.”
So I built Your Finance Guide to be the benchmark.
I spent more than a decade in the property industry advising buyers and investors, and I got tired of seeing people get ripped off. So every broker here has sat with me for over two hours, and we have checked their references, reviews and accreditations, before they hear from you.
 Andy McMasterFounder, Your Finance Guide · Why I built it
Chattel mortgage questions
What is a chattel mortgage?
A chattel mortgage is a business loan to buy a vehicle, with the vehicle as security. The business owns the vehicle from the day it buys it, and the lender holds a mortgage over it until the loan is repaid. Repayments are set for the term, and a balloon at the end can lower them.
Chattel mortgage, lease or hire purchase: what’s the difference?
With a chattel mortgage the business owns the vehicle from day one. With a commercial hire purchase the lender owns it until the last payment, then it passes to the business. With a finance lease the lender owns it and the business pays to use it, with a residual at the end. GST and tax work differently for each, so ask your accountant which suits you. We help with loans: chattel mortgage and hire purchase, not leases.
What’s a balloon payment, and how does it change my repayments?
A balloon is a lump sum left to the end of the loan. It lowers each repayment, because less of the loan is paid off during the term, but you pay more interest overall. On a $50,000 vehicle over 5 years at an example rate of 8.5%, a 30% balloon takes the monthly repayment from about $1,026 to about $824, and leaves $15,000 to pay at the end. The balloon has to be paid, refinanced or covered by selling the vehicle when it falls due.
Can I claim the GST or a tax deduction?
General information only: if the business is registered for GST and buys the vehicle with a chattel mortgage, the GST in the price may be claimable on its next BAS, and the interest and depreciation may be deductible. Limits apply to cars, and it depends on how the business uses the vehicle, so talk to your accountant.
Can I get finance with a new ABN?
Often, yes. Many lenders prefer an ABN that has been active for two years, but there are lenders for newer businesses, usually with a deposit, GST registration, property ownership or a clean credit file working in your favour. A broker knows which lenders take new ABNs and what they ask for.
Do I need a deposit?
Not always. Some lenders finance the full price for an established business with a clean credit file. A deposit or trade-in lowers what you borrow and what you repay, and it can open up more lenders for a newer business, an older vehicle or a credit file with marks on it.
Does this calculator or the quiz affect my credit score?
No. There’s no credit check to start. The calculator works in your browser, and the quiz only decides which broker should call you. A lender checks your credit only if you decide to apply.
What can I finance?
Cars, utes, vans and trucks, new or used, from a dealer or a private seller. Lenders set age limits for used vehicles, and a private sale needs a few more checks, which your broker takes you through.
See what lenders could offer your business
Your numbers are ready to go. Answer a few questions and a licensed broker finds the lenders that fit yours.
General information, not a credit offer. Your Finance Guide is a finance education publisher. We are not a credit provider, broker, or lender, we do not hold an Australian Credit Licence, and we do not provide credit assistance. When you request a quote, your enquiry goes to a licensed broker who meets our criteria and compares rates from a panel of Australian lenders. Full details, including the licence we work in conjunction with, are in our Credit Guide. Your Finance Guide is free to use. Licensed brokers who meet our criteria pay Your Finance Guide a partnership fee to receive enquiries from this site. The fee is paid by the broker, not by you, and is not added to your loan. Brokers are usually also paid a commission by the lender when a loan settles. Full details are in our Credit Guide.
Your Finance Guide is the publishing brand and is not licensed to provide credit assistance. Credit assistance is provided by the licensed broker you are introduced to, who holds an Australian Credit Licence or is a credit representative of a licensee.
The rate in the calculator is an example, not a rate any lender has offered you. Business loans and equipment finance for a business purpose are not covered by the National Credit Code, so lenders do not have to publish a comparison rate for them. A business rate may not include fees and charges: ask the lender or broker for the total cost, fees included, before you compare.
Read our Credit Guide. Questions: hello@yourfinanceguide.com.au