A few quick questions. About 2 minutes.
Check your home loan refinance options
One YFG Approved mortgage broker compares your loan, and must act in your best interests.
- No credit check at this step
- Free, no obligation
- YFG Approved broker

Every mortgage broker here is YFG Approved. Our founder, Andy McMaster, spends over two hours with each one, and we check their references, reviews and licence before they hear from you. How we vet
Still paying more than you need to? Tell us what the home is worth and what you owe. Your Finance Guide connects you with one licensed mortgage broker, who compares lenders against your current loan and calls within one business day.
What you owe, and what the home is worth
Best guesses are fine. A recent sale nearby is a good guide to the value.
Free matching, no obligation and no credit check at this step.
Three steps, and you sign nothing until you’re sure.
Your loan, in about two minutes
What you owe, what the home is worth and the rate you pay. No credit check at this step, no account.
One YFG Approved broker
A broker who has passed every check calls within one business day, already knowing your answers. You can pick a time that suits you.
You decide
They compare lenders on their panel and explain, in writing, why a loan suits you. No obligation, and if anything feels off, tell us.
About two minutes. Free, with no obligation to go ahead.
Why we check the broker before the rate
The rate on the sign is rarely the rate people pay, and a licence is only the start. Two numbers, from the people who keep them.
between the banks’ standard variable rate and what new borrowers actually pay.
The standard rate is 8.77%. The average new variable home loan is 6.23%. On a $600,000 loan over 30 years, that gap is about $1,040 a month. The price of a home loan is negotiated, and it depends on who is asking.
people banned or disqualified by ASIC from credit work.
176 of those bans are still in force. Rules catch people after the damage is done, which is why a licence is where our checks start, not where they end.
So we check the broker first.
Sources: Reserve Bank of Australia, statistical tables F5 (September 2026) and F6 (August 2026). ASIC Banned and Disqualified Persons register (credit), data.gov.au, 19 October 2026. Checked 21 October 2026.
Before you sign, know what you’re looking at
A good broker goes through an offer line by line, and explains why it suits you. This is what that conversation covers.
- Why the loan suits you, and for a home loan, in writing
- The comparison rate and every fee, not only the headline rate
- What leaving your current loan costs, and when a switch pays for itself
- What happens to the rate after any honeymoon or fixed period
- The features you actually use, like an offset or redraw
About two minutes. Free, with no obligation to go ahead.
Example Lender
Home loan offer
Offer valid for 30 days
- Loan amount$600,000
- Variable rate5.89% p.a.AskThe headline rate. Ask for the comparison rate too.
- Comparison rate*6.14% p.a.AskFees included. This is the one to compare.
- Package fee$395 a yearAskWorth it only if you use what it pays for.
- Offset accountIncludedAskFull offset, or partial?
- Cashback$3,000AskAny conditions if you leave early?
- Leaving your current lenderDischarge fee appliesAskWhat does switching cost, all in?
- Monthly repayment$3,555
An example offer. Not a real lender, rate or customer. Repayment is principal and interest over 30 years. *WARNING: This comparison rate is true only for the examples given and may not include all fees and charges. Different terms, fees or other loan amounts might result in a different comparison rate.
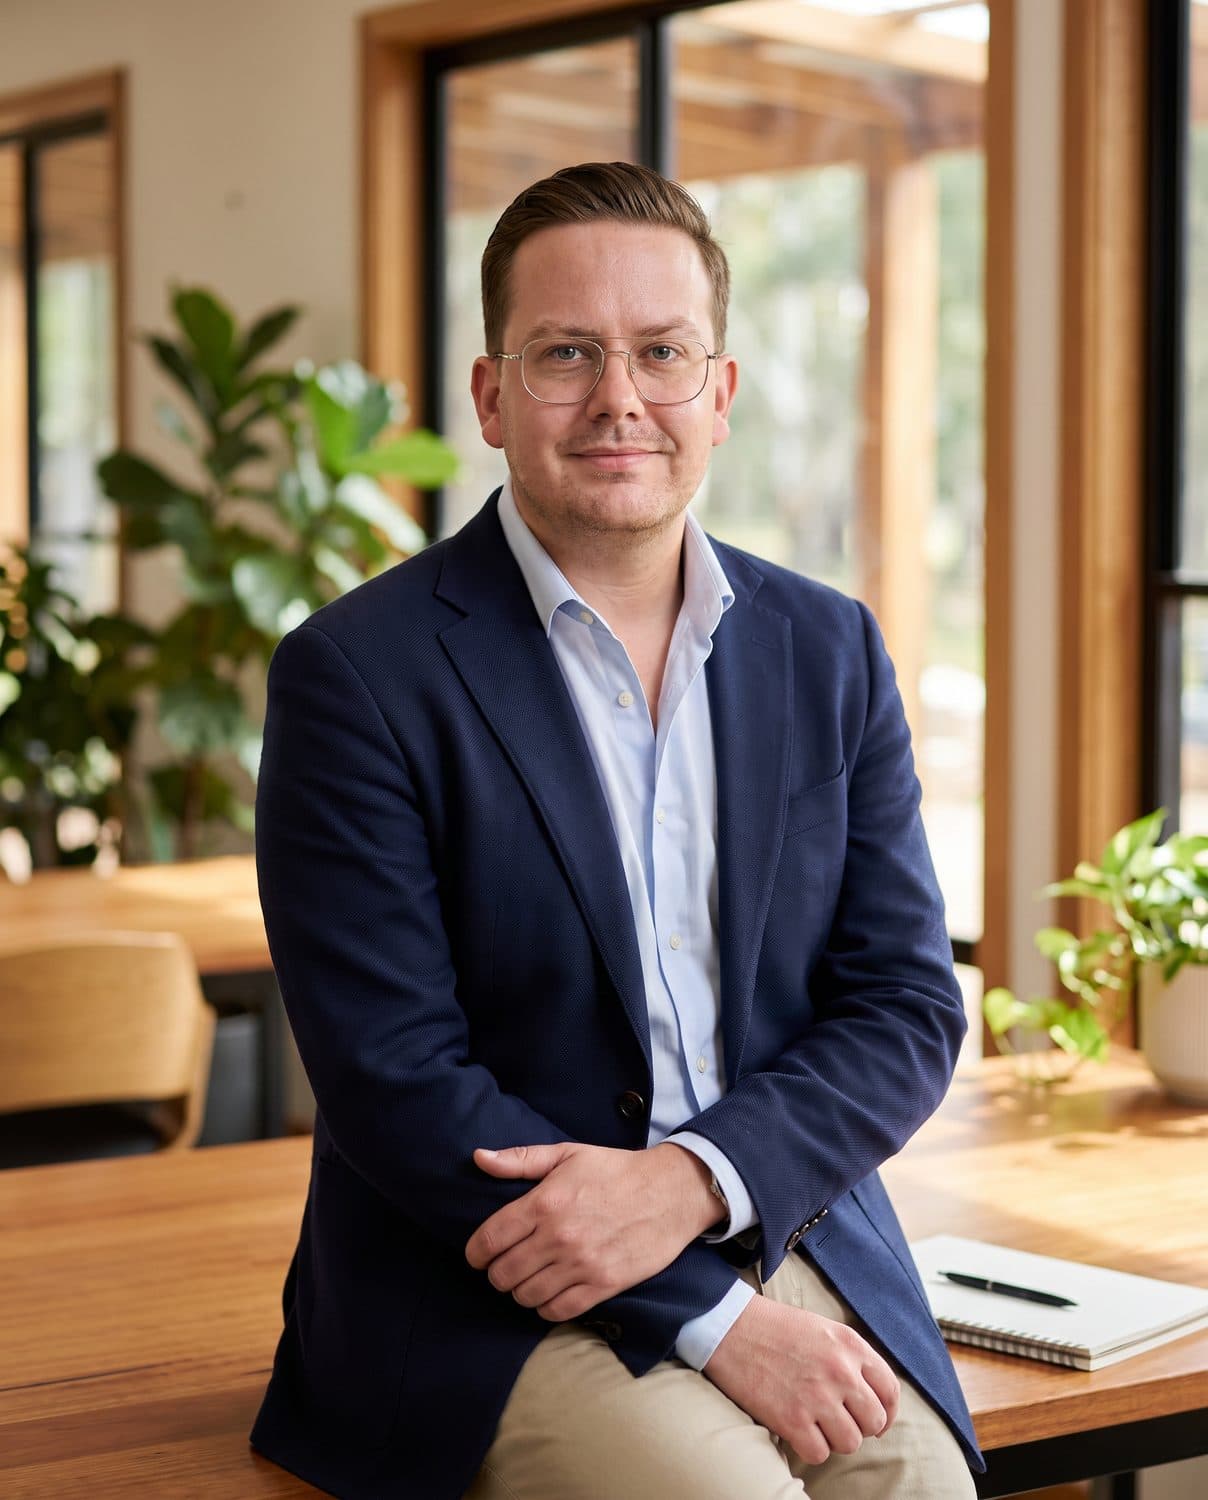
“I got tired of seeing people get ripped off.”
So I built Your Finance Guide to be the benchmark.
I spent more than a decade in the property industry advising buyers and investors, and I got tired of seeing people get ripped off. So every broker here has sat with me for over two hours, and we have checked their references, reviews and accreditations, before they hear from you.
Andy McMasterFounder, Your Finance Guide · Why I built itBrokers earn the YFG approval. They can lose it.
A licence is the minimum, not the standard. Before a broker hears from a single borrower they pass six checks, and they have to keep passing them. It takes us hours per broker, and it’s meant to.
Paying us doesn’t buy approval. A broker who fails a check doesn’t get enquiries at any price.
The YFG Approved standard: six checks
Two hours with the founder
Andy spends over two hours with every broker: how they work, how they write loans and how they look after people. If they can’t show they know their profession, it ends there.
References checked
We speak to people who have worked with them, so we hear how they operate when nobody is selling.
Reviews read
We read what their clients say about them in public, the hard reviews as well as the good ones.
Licence and accreditations
Their Australian Credit Licence or credit representative number, looked up on ASIC’s register, membership of AFCA (the free complaints scheme) and their accreditations.
Bound to act in your best interests
By law a mortgage broker has to put your interests first and explain why a loan suits you. We hold them to it, and they call within one business day.
Answerable to you
If a broker doesn’t call, doesn’t explain your options or doesn’t treat you well, tell us. We follow up every report, and a broker who falls short loses their YFG approval.
“We check every broker. I spend over two hours with each one to make sure they understand their profession, know how to write loans and get people what they need.”Andy McMaster, founder
Licensed brokers who meet our criteria pay Your Finance Guide a partnership fee to receive enquiries from this site. The fee is paid by the broker, not by you, and is not added to your loan. Read our Credit Guide.
Seven questions to ask any broker
Ours included. Take them to every broker you speak to, before you sign anything.
How many lenders are on your panel, and how many did you compare for me?
Two or three is not a comparison.
Why is this loan in my best interests? Can I have that in writing?
By law a mortgage broker has to work that out. Asking for it is fair.
How are you paid on this loan, and would another lender pay you differently?
Commission is normal. Being told about it is the test.
What is the comparison rate, and which fees make the difference?
What does leaving my current lender cost: discharge fees, break costs or a cashback clawback?
What happens to the rate when any honeymoon or fixed period ends?
Does the new loan keep what I use, like an offset account or redraw?
If they hesitate, ask why.
A good broker answers all seven without hesitating. Every YFG Approved broker expects to be asked.
Your broker compares lenders like...
Lenders your broker can compare include Commonwealth Bank, Westpac, ANZ, Macquarie, ING, Bankwest, Suncorp Bank, AMP, ME Bank, Bendigo Bank, Liberty.
Examples of lenders on the partner broker’s panel. Which ones are open to you depends on your circumstances, and no lender can be promised.
Home loans, explained
What does YFG Approved mean?
Every broker we introduce has spent over two hours one on one with our founder, Andy McMaster, showing they know their profession and how to write loans. We check their references, their client reviews and their accreditations, and look up their licence or credit representative number on ASIC’s register. If a broker falls short, tell us: we follow up every report, and a broker who falls short loses their approval.
How much deposit do I need for a home loan?
Twenty per cent of the price avoids lenders mortgage insurance and opens the sharpest rates. Most lenders will go to a 5 per cent deposit with insurance added, and the federal 5 per cent deposit guarantee lets eligible first home buyers skip the insurance. Gifts, grants and a family guarantee can all count. The check works this out from your price and deposit.
What is LVR and why does it matter?
Loan-to-value ratio: the loan as a percentage of what the property is worth. A $560,000 loan on a $700,000 home is 80 per cent. Lenders price on it. Under 80 per cent usually means no lenders mortgage insurance and the widest choice of lenders; above it, fewer lenders and an insurance premium unless a guarantee covers you.
What can a first home buyer get?
Depending on the state, a first home owner grant on a new build, a stamp duty concession or exemption, and access to the federal 5 per cent deposit guarantee. Some states add shared equity schemes. They stack, and they change often, so the broker checks which apply to you and the property before you commit.
How much can I borrow?
Roughly five to six times household income after existing debts, tested at a rate about three percentage points above the actual one, then capped by your deposit and the property’s value. Two lenders can differ by six figures on the same income because they treat bonuses, overtime, rental income and living costs differently, which is where a broker earns their keep.
What documents do I need to apply?
Photo ID, two recent payslips or two years of tax returns if you are self-employed, three months of bank statements, evidence of your deposit, and statements for any existing loans or cards. For a refinance, add your current loan statements and a rates notice. Most of it is read electronically now.
How does refinancing work and what does it cost?
The new lender pays out the old loan and you start repaying them instead. Usually a discharge fee from the old lender, government registration fees, and sometimes an application or valuation fee with the new one; break costs can apply if you leave a fixed rate early. Many lenders offset these with a cashback or fee waiver. The broker sets the costs against the saving before you decide.
How quickly can I get approved?
It depends on the lender, your documents and the valuation, and nobody can promise a time before a lender has assessed the application. A pre-approval is usually quicker than a full approval, and a refinance runs on a similar timeline to a purchase. The broker calls within one business day of your check, already knowing your answers, so the clock starts sooner.
Is this a credit check?
No. Your answers only decide which broker should call you. Nothing is sent anywhere until you submit your details, and even then no credit enquiry happens until you authorise a specific lender application.
How does Your Finance Guide make money?
Licensed brokers who meet our criteria pay Your Finance Guide a partnership fee to receive enquiries from this site. The fee is paid by the broker, not by you, and is not added to your loan. You never pay us. Brokers are usually also paid a commission by the lender when a loan settles, so ask the broker you speak with how they are paid. Full details are in our Credit Guide.
Check the broker. Then check the rate.
About two minutes to compare your loan. Free, and nothing to sign until you’re sure.
What every match includes
- One YFG Approved broker, not a list
- A call within one business day, at a time you can pick
- A broker bound by law to act in your best interests
- No cost to you, and no obligation
- Your answers, so the first call starts with your options
- Someone to tell if anything goes wrong: us