Chattel Mortgage for Your Business Vehicle
Answer a few quick questions and see your estimated repayments.
- No credit check at this step
- Free, no obligation
- One call, not ten

Every finance broker here is YFG Approved. Our founder, Andy McMaster, spends over two hours with each one, and we check their references, reviews and licence before they hear from you. How we vet
Want the business to own the vehicle from day one? Your Finance Guide connects Australian businesses with a licensed broker partner who compares chattel mortgage and hire purchase lenders for you.
What are you financing?
Pick the closest match.
Free matching, no obligation and no credit check at this step.
How a chattel mortgage works
A chattel mortgage is a business loan to buy a vehicle, with the vehicle as security. The business owns the vehicle from day one, and the lender holds a mortgage over it until the loan is repaid.
Chattel mortgage or commercial hire purchase. Under a commercial hire purchase the lender buys the vehicle and the business pays it off, owning it only once the final payment is made. A chattel mortgage gives the business ownership at the start. The repayments can look much the same; the difference is when the business owns the vehicle.
GST. If the business is registered for GST, the GST in the purchase price may be claimable on your next BAS when you buy under a chattel mortgage. Check with your accountant how it applies to your business.
Terms and balloon payments. Terms usually run from one to seven years. A balloon payment, a lump sum left to the end of the loan, lowers the monthly repayment but costs more interest overall, and has to be paid, refinanced or covered by selling the vehicle when it falls due.
This service is for loans, not leases. A licensed broker partner compares chattel mortgage and hire purchase lenders for your business and calls within one business day. There is no credit check at this step.
Brokers earn the YFG approval. They can lose it.
A licence is the minimum, not the standard. Before a broker hears from a single borrower they pass six checks, and they have to keep passing them. It takes us hours per broker, and it’s meant to.
Paying us doesn’t buy approval. A broker who fails a check doesn’t get enquiries at any price.
The YFG Approved standard: six checks
Two hours with the founder
Andy spends over two hours with every broker: how they work, how they write loans and how they look after people. If they can’t show they know their profession, it ends there.
References checked
We speak to people who have worked with them, so we hear how they operate when nobody is selling.
Reviews read
We read what their clients say about them in public, the hard reviews as well as the good ones.
Licence and accreditations
Their Australian Credit Licence or credit representative number, looked up on ASIC’s register, membership of AFCA (the free complaints scheme) and their accreditations.
Held to our rules
Your enquiry goes to them alone, not to a list, and they call within one business day, already knowing your answers.
Answerable to you
If a broker doesn’t call, doesn’t explain your options or doesn’t treat you well, tell us. We follow up every report, and a broker who falls short loses their YFG approval.
“We check every broker. I spend over two hours with each one to make sure they understand their profession, know how to write loans and get people what they need.”Andy McMaster, founder
Licensed brokers who meet our criteria pay Your Finance Guide a partnership fee to receive enquiries from this site. The fee is paid by the broker, not by you, and is not added to your loan. Read our Credit Guide.
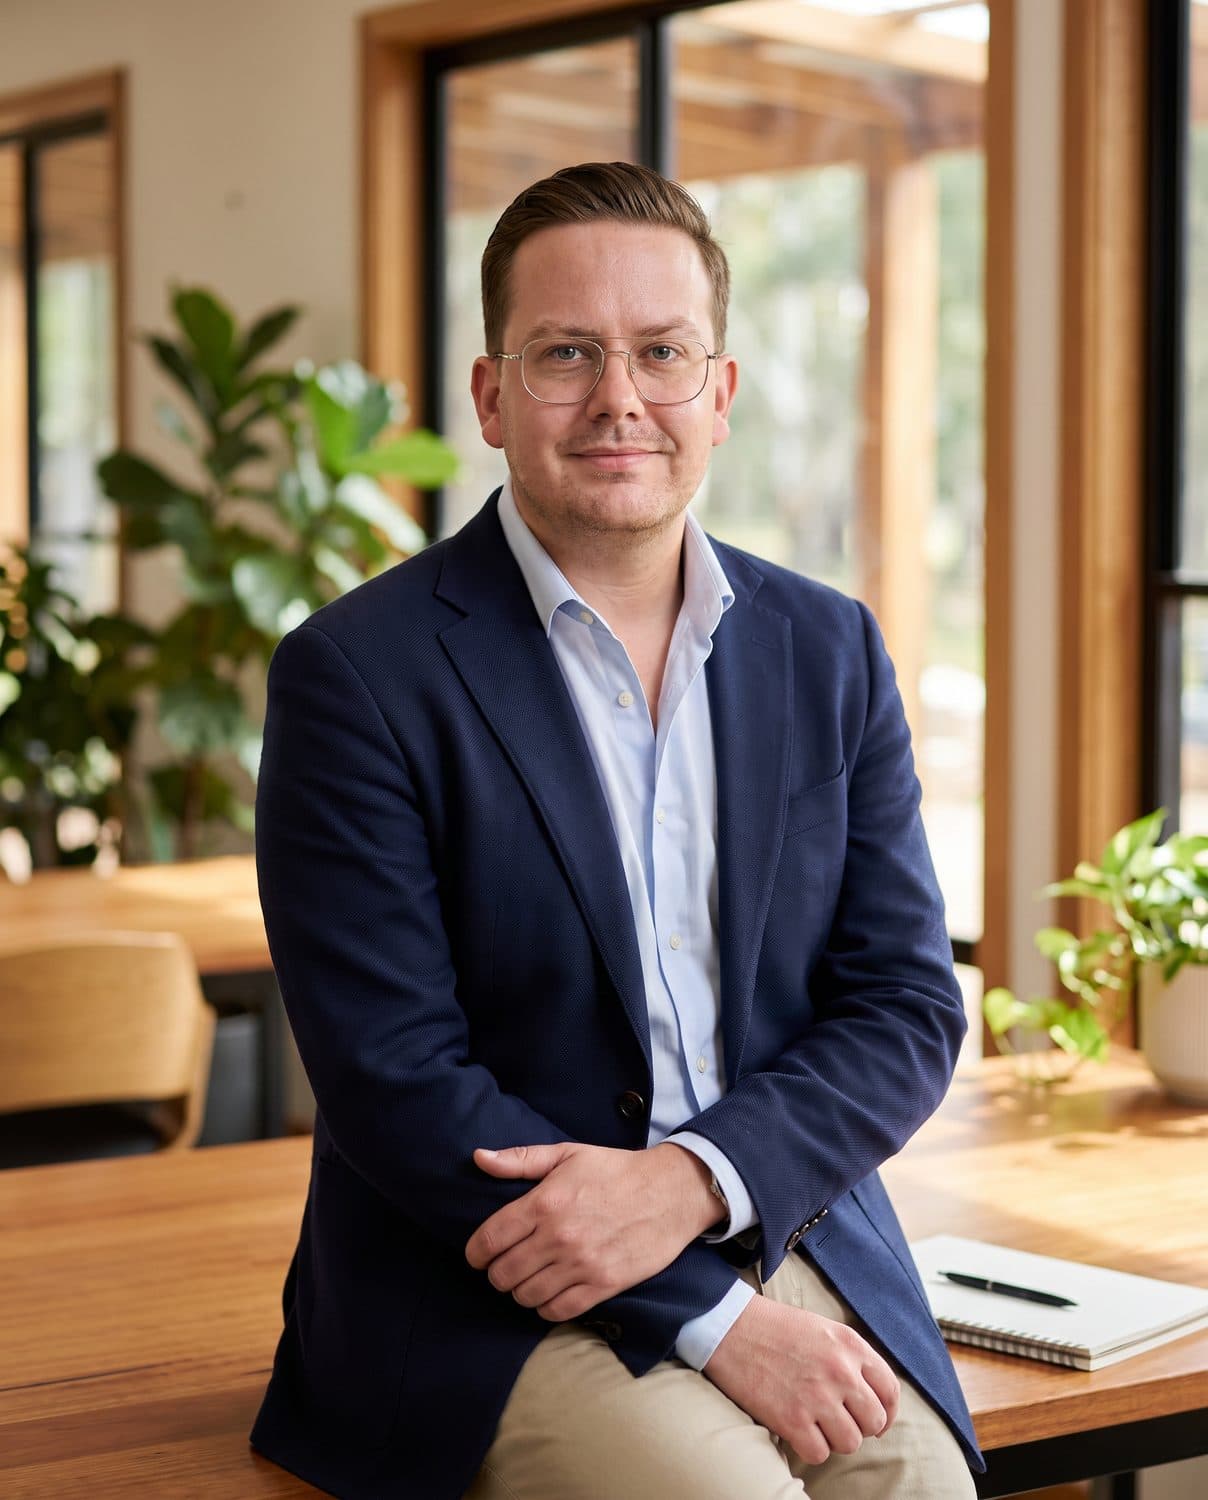
“I got tired of seeing people get ripped off.”
So I built Your Finance Guide to be the benchmark.
I spent more than a decade in the property industry advising buyers and investors, and I got tired of seeing people get ripped off. So every broker here has sat with me for over two hours, and we have checked their references, reviews and accreditations, before they hear from you.
Andy McMasterFounder, Your Finance Guide · Why I built itYour broker compares lenders like...

Lenders your broker can compare include Prospa, Moula, OnDeck, Judo Bank, Angle Finance, Latitude, Capify, Earlypay, Plenti, Liberty, Macquarie, Westpac, ANZ.
Examples of lenders on the partner broker’s panel. Which ones are open to you depends on your circumstances, and no lender can be promised.
How it works
Step 1: Answer a few quick questions
About a minute, no credit check at this step.
Step 2: See your estimated repayments
Confirm your mobile and they appear straight away.
Step 3: Talk to one finance broker
They compare lenders and give you your actual rate. No obligation.
See your estimated repayments
Start nowWe don’t lend, and we don’t sell finance.
Your Finance Guide is a finance education publisher. We are not a lender, a broker or a credit provider. This check exists because the first thing most owners hear from a lender is a decline, after a hard credit enquiry, when a five-minute read of policy would have pointed them at the right lender to begin with.
So the check costs nothing and takes about a minute. Then we connect you with a licensed broker who works your kind of lending. They call within one business day, already knowing your answers, so the conversation starts at the right lender instead of at square one.
Frequently asked questions
Who is this for?
Businesses buying a car, ute, van, truck or trailer that will be used more than half the time for the business, and that want to own it from day one. Sole traders, companies and trusts with an ABN.
Do you check my credit?
Not at this step. A lender may if you apply.
Who will call me?
A licensed broker partner who compares chattel mortgage and hire purchase lenders, usually within one business day, already knowing your answers.
Do I pay anything?
No. Licensed brokers who meet our criteria pay Your Finance Guide a partnership fee to receive enquiries from this site. The fee is paid by the broker, not by you, and is not added to your loan.
Is this a lease?
No. A chattel mortgage is a loan: the business owns the vehicle from day one. We only help with loans such as chattel mortgage and hire purchase.
See your estimated repayments
Start now