Business Car Loans for ABN Holders
Answer a few quick questions and see your estimated repayments.
- No credit check at this step
- Free, no obligation
- One call, not ten

Every finance broker here is YFG Approved. Our founder, Andy McMaster, spends over two hours with each one, and we check their references, reviews and licence before they hear from you. How we vet
A car the business will use, not just a car for home? Your Finance Guide connects ABN holders with a licensed broker partner who compares business car loans from bank and non-bank lenders.
No credit check to start · Free · No obligation
Roughly how much do you need?
A rough figure is fine.
Brokers earn the YFG approval. They can lose it.
A licence is the minimum, not the standard. Before a broker hears from a single borrower they pass six checks, and they have to keep passing them. It takes us hours per broker, and it’s meant to.
Paying us doesn’t buy approval. A broker who fails a check doesn’t get enquiries at any price.
The YFG Approved standard: six checks
Two hours with the founder
Andy spends over two hours with every broker: how they work, how they write loans and how they look after people. If they can’t show they know their profession, it ends there.
References checked
We speak to people who have worked with them, so we hear how they operate when nobody is selling.
Reviews read
We read what their clients say about them in public, the hard reviews as well as the good ones.
Licence and accreditations
Their Australian Credit Licence or credit representative number, looked up on ASIC’s register, membership of AFCA (the free complaints scheme) and their accreditations.
Held to our rules
Your enquiry goes to them alone, not to a list, and they call within one business day, already knowing your answers.
Answerable to you
If a broker doesn’t call, doesn’t explain your options or doesn’t treat you well, tell us. We follow up every report, and a broker who falls short loses their YFG approval.
“We check every broker. I spend over two hours with each one to make sure they understand their profession, know how to write loans and get people what they need.”Andy McMaster, founder
Licensed brokers who meet our criteria pay Your Finance Guide a partnership fee to receive enquiries from this site. The fee is paid by the broker, not by you, and is not added to your loan. Read our Credit Guide.
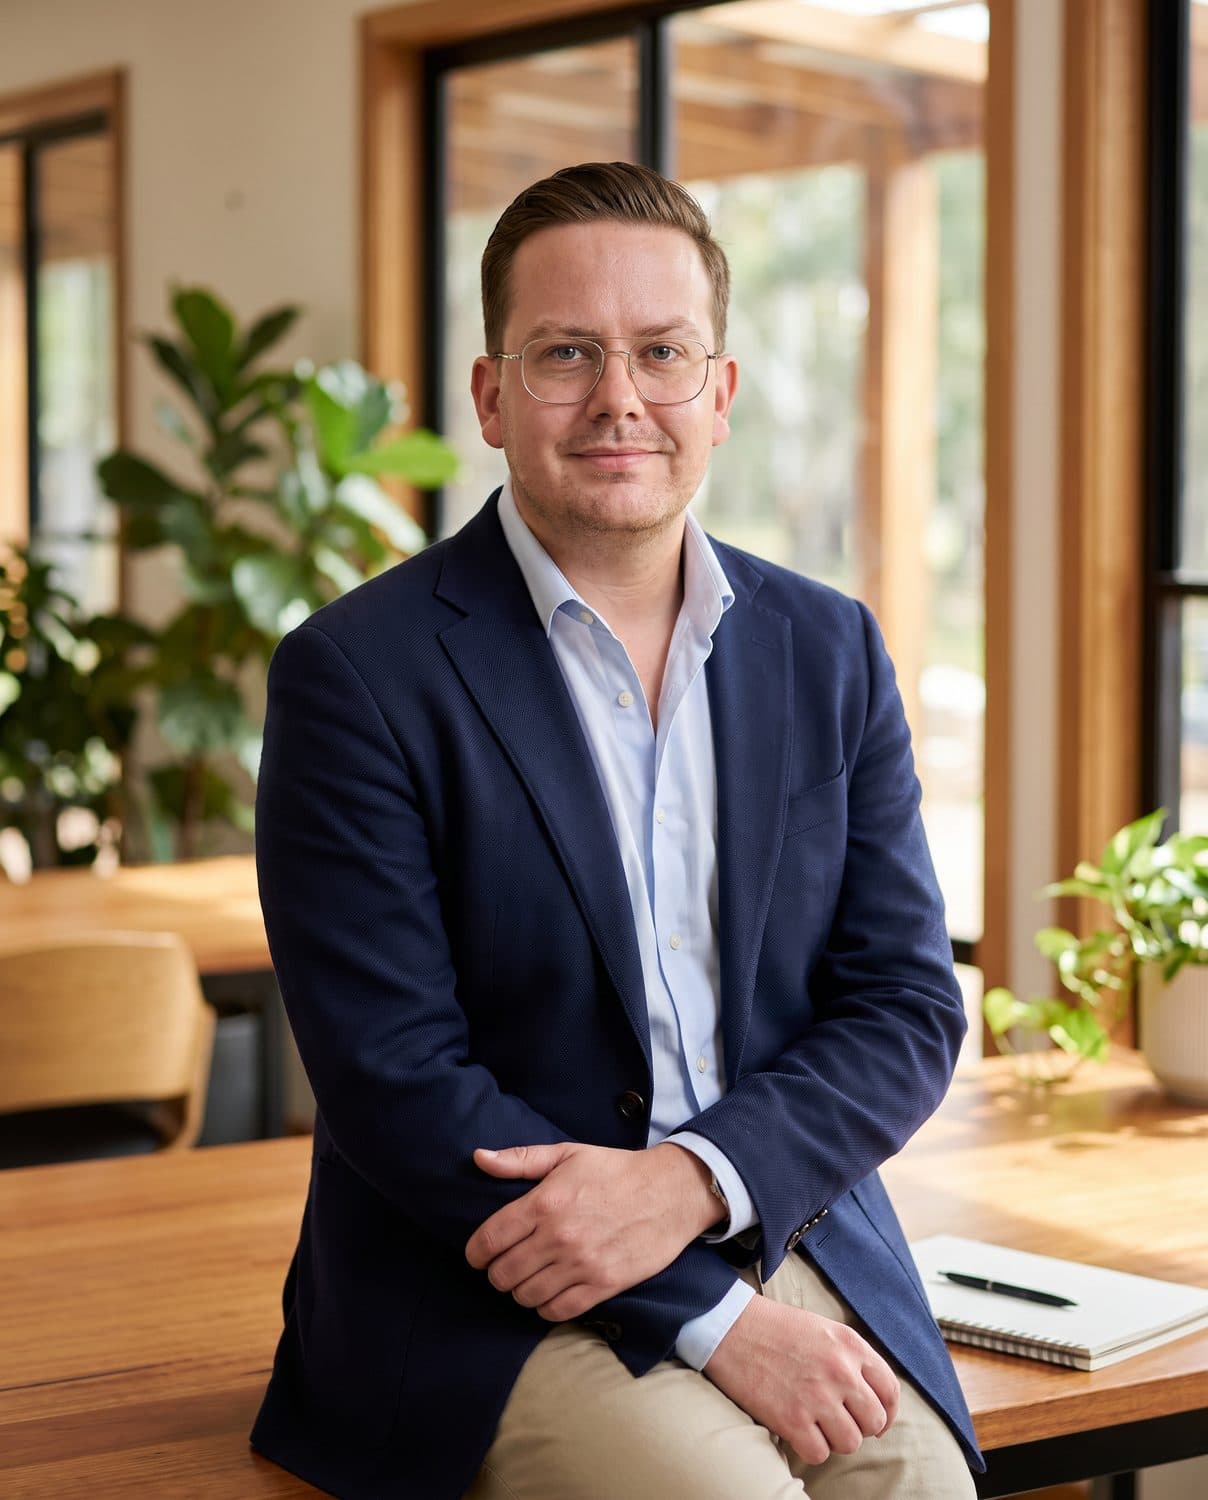
“I got tired of seeing people get ripped off.”
So I built Your Finance Guide to be the benchmark.
I spent more than a decade in the property industry advising buyers and investors, and I got tired of seeing people get ripped off. So every broker here has sat with me for over two hours, and we have checked their references, reviews and accreditations, before they hear from you.
Andy McMasterFounder, Your Finance Guide · Why I built itYour broker compares lenders like...

Lenders your broker can compare include Prospa, Moula, OnDeck, Judo Bank, Angle Finance, Latitude, Capify, Earlypay, Plenti, Liberty, Macquarie, Westpac, ANZ.
Examples of lenders on the partner broker’s panel. Which ones are open to you depends on your circumstances, and no lender can be promised.
How it works
Step 1: Answer a few quick questions
About a minute, no credit check at this step.
Step 2: See your estimated repayments
Confirm your mobile and they appear straight away.
Step 3: Talk to one finance broker
They compare lenders and give you your actual rate. No obligation.
See your estimated repayments
Start nowWe don’t lend, and we don’t sell finance.
Your Finance Guide is a finance education publisher. We are not a lender, a broker or a credit provider. This check exists because the first thing most owners hear from a lender is a decline, after a hard credit enquiry, when a five-minute read of policy would have pointed them at the right lender to begin with.
So the check costs nothing and takes about a minute. Then we connect you with a licensed broker who works your kind of lending. They call within one business day, already knowing your answers, so the conversation starts at the right lender instead of at square one.
Frequently asked questions
What is business vehicle finance?
A loan for a car, ute, van, truck, trailer or bus the business will use, with the vehicle as the security. Because the lender can take the vehicle back, it prices lower than an unsecured loan and is often approved from your ABN history, credit file and the quote alone. You drive it from day one and pay it off over two to seven years.
Chattel mortgage or hire purchase: which one?
A chattel mortgage is the most common for businesses: the business owns the vehicle from day one, and if it is registered for GST, the GST in the price may be claimable on the next BAS (check with your accountant). A commercial hire purchase transfers ownership once the last payment is made. The broker matches the structure to your business and how long you will keep the vehicle. This service is for loans, not leases.
Can I finance a used vehicle or a private sale?
Yes. Most lenders finance used vehicles as long as the vehicle is inside their age limit at the end of the term, commonly 12 to 20 years. A private sale adds an inspection, a PPSR check for finance owing, and a contract that matches the valuation; dealer and auction purchases are simpler.
What is a balloon payment and should I have one?
A lump sum left to the end of the loan, often 20 to 40 per cent of the price, which lowers the monthly repayment. It suits a vehicle you plan to sell or trade at the end of the term, since the sale covers the balloon. It costs more interest over the life of the loan, and the balloon has to be paid, refinanced or covered by the sale when it falls due.
Am I eligible for vehicle finance?
Most low-doc products want an ABN active for two years, GST registration, a clean credit file and either property ownership or a deposit of 10 to 20 per cent. Newer businesses, older vehicles and imperfect credit are still fundable, usually with a deposit, a shorter term or a specialist lender. The check gives the broker exactly these facts.
What documents do I need to apply?
For a low-doc approval on a standard vehicle, usually photo ID, your ABN and GST details, and the dealer quote or invoice. Larger amounts, a private sale or a newer ABN add bank statements, financials or a valuation.
Can I refinance my existing vehicle loan?
Yes. Refinancing to a lower rate, extending the term to ease cash flow, or refinancing a vehicle you own outright to release cash are all common. Tell the broker what you have now and they will set the cost of switching against the saving.
How quickly can I get approved?
It depends on the lender, the vehicle and your documents, and nobody can promise a time before a lender has assessed the application. A low-doc application on a standard vehicle is usually quicker than an older vehicle, a private sale or a full-doc file. The broker calls within one business day of your check, already knowing your answers, so the clock starts sooner.
Is this a credit check?
Not at this step. Your answers only decide which broker should call you, and no credit enquiry happens unless you authorise a specific lender application.
How does Your Finance Guide make money?
Licensed brokers who meet our criteria pay Your Finance Guide a partnership fee to receive enquiries from this site. The fee is paid by the broker, not by you, and is not added to your loan. You never pay us. Brokers are usually also paid a commission by the lender when a loan settles, so ask the broker you speak with how they are paid. Full details are in our Credit Guide.
See your estimated repayments
Start now