A few quick questions. About a minute.
Clear an ATO debt with a business loan
See how a loan compares with the ATO’s interest charge. A few quick questions, no credit check at this step.
- No credit check at this step
- Free, no obligation
- YFG Approved broker
We’re not affiliated with the ATO and don’t negotiate with it or give tax advice. The ATO may offer a payment plan (ato.gov.au), which could cost less.

Every broker here is YFG Approved. Our founder, Andy McMaster, spends over two hours with each one, and we check their references, reviews and licence before they hear from you. How we vet
Tell us what is owed and where it stands with the ATO. Your Finance Guide connects you with one licensed broker who arranges business loans, sets the options against a payment plan, and calls within one business day.
No credit check to start · Free · No obligation
How much is owed to the ATO?
Your ATO online account or your tax agent will have the balance. A band is enough.
Business loans for ATO debts: amounts, terms and costs
What the business lenders our brokers work with publish. Business loans sit outside the National Credit Code, so lenders don’t have to publish comparison rates; the example’s is worked out the same way, fees included.
- Loan amounts
- $5,000 to $500,000
- Repayment period
- Minimum 3 months, maximum 5 years
- Maximum annual percentage rate
- 35.99% p.a.The highest interest rate the lenders we checked publish. Establishment fees, usually 2% to 3.5% of the loan, are on top.
- Representative example
- Business loan, unsecured, $50,000 over 3 years at 15.95% p.a., comparison rate 17.72% p.a.*, establishment fee $1,250 (added to the loan), monthly fee $0, 36 monthly repayments of $1,800.53, total repayable $64,819.08.
*WARNING: This comparison rate is true only for the examples given and may not include all fees and charges. Different terms, fees or other loan amounts might result in a different comparison rate.
Rates and fees as at 13 October 2026. Your actual rate, fees and repayments depend on the lender’s assessment. This is not an offer of credit.
Brokers earn the YFG approval. They can lose it.
A licence is the minimum, not the standard. Before a broker hears from a single borrower they pass six checks, and they have to keep passing them. It takes us hours per broker, and it’s meant to.
Paying us doesn’t buy approval. A broker who fails a check doesn’t get enquiries at any price.
The YFG Approved standard: six checks
Two hours with the founder
Andy spends over two hours with every broker: how they work, how they write loans and how they look after people. If they can’t show they know their profession, it ends there.
References checked
We speak to people who have worked with them, so we hear how they operate when nobody is selling.
Reviews read
We read what their clients say about them in public, the hard reviews as well as the good ones.
Licence and accreditations
Their Australian Credit Licence or credit representative number, looked up on ASIC’s register, membership of AFCA (the free complaints scheme) and their accreditations.
Held to our rules
Your enquiry goes to them alone, not to a list, and they call within one business day, already knowing your answers.
Answerable to you
If a broker doesn’t call, doesn’t explain your options or doesn’t treat you well, tell us. We follow up every report, and a broker who falls short loses their YFG approval.
“We check every broker. I spend over two hours with each one to make sure they understand their profession, know how to write loans and get people what they need.”Andy McMaster, founder
Licensed brokers who meet our criteria pay Your Finance Guide a partnership fee to receive enquiries from this site. The fee is paid by the broker, not by you, and is not added to your loan. Read our Credit Guide.
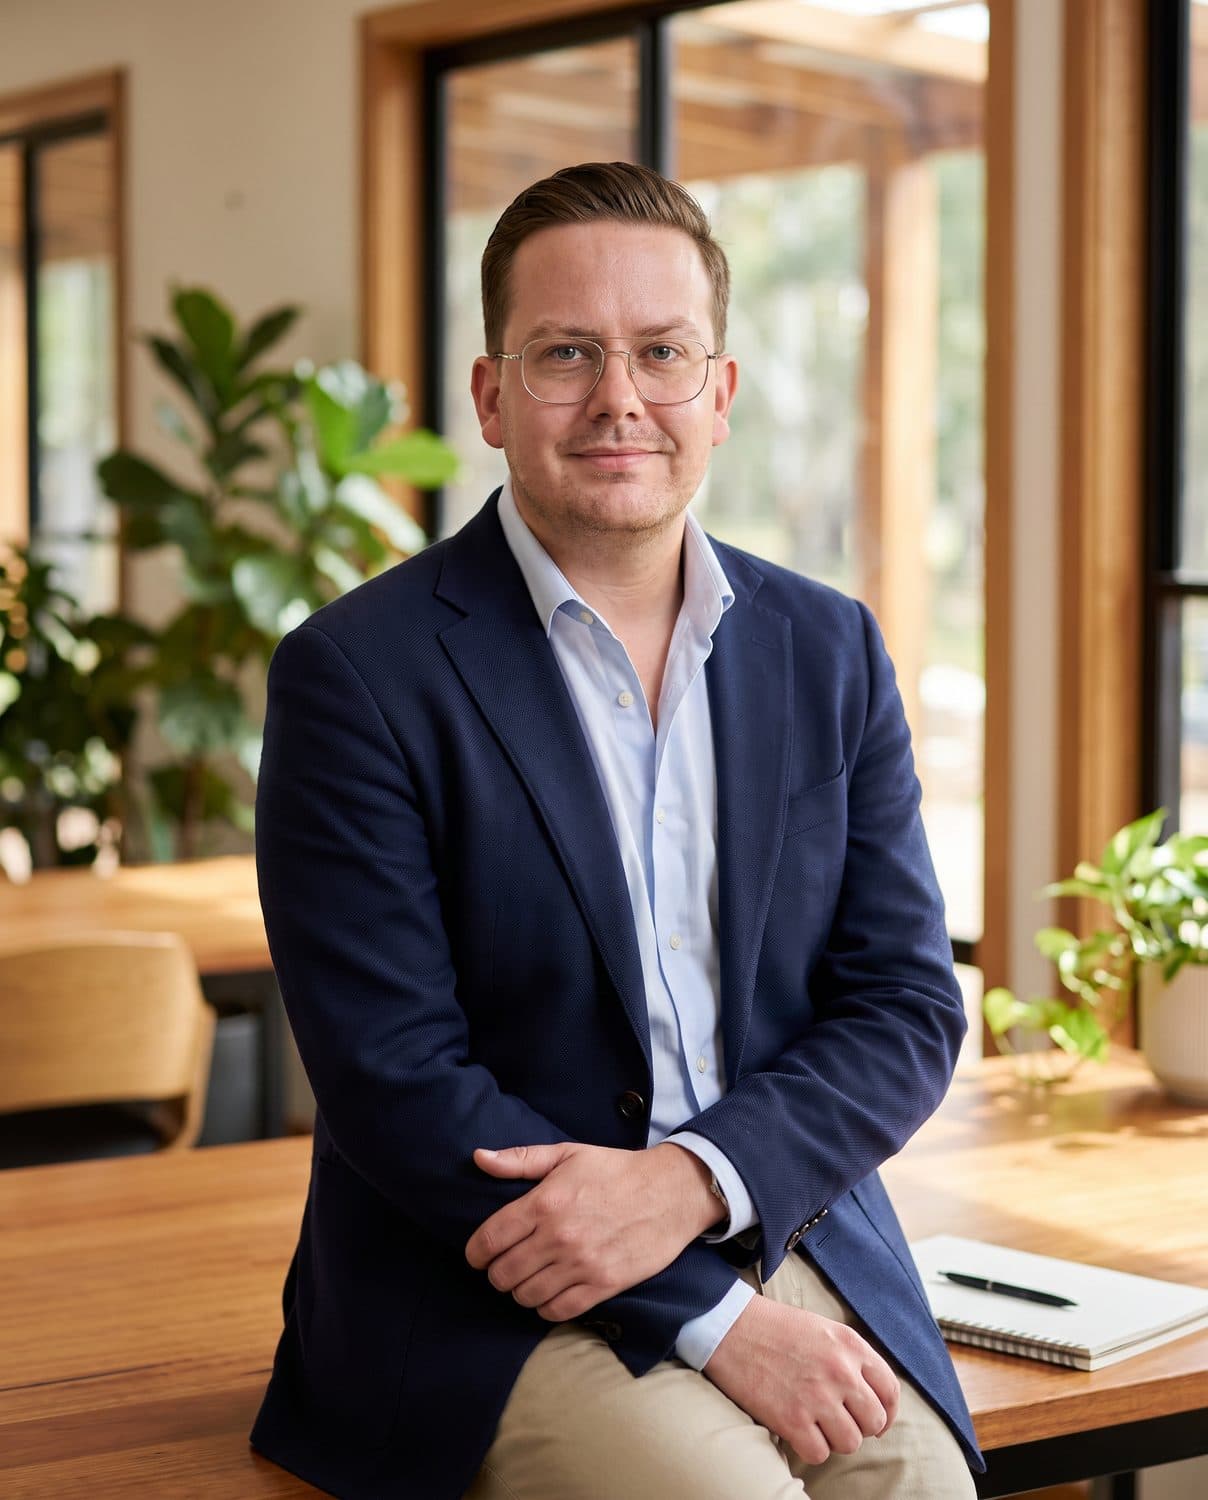
“I got tired of seeing people get ripped off.”
So I built Your Finance Guide to be the benchmark.
I spent more than a decade in the property industry advising buyers and investors, and I got tired of seeing people get ripped off. So every broker here has sat with me for over two hours, and we have checked their references, reviews and accreditations, before they hear from you.
Andy McMasterFounder, Your Finance Guide · Why I built itHow it works
Step 1: Answer a few quick questions
What is owed, the kind of tax debt and your business on the ABN register. About a minute.
Step 2: See the comparison
Confirm your mobile and the ATO’s interest charge appears beside indicative loan repayments.
Step 3: Talk to one licensed broker
They call within one business day and compare lenders for you. No obligation.
Compare a loan with the ATO’s interest charge
Start nowATO debt and business loans: common questions
Is a business loan cheaper than an ATO payment plan?
Not always. On a payment plan the ATO still charges its general interest charge, 11.51% a year for October to December 2026, compounding daily. Unsecured business loans often cost more than that; a loan secured on property can cost less. A loan can make sense when the ATO won’t agree a plan, a plan has defaulted, or you want the ATO paid out and one repayment to a lender. The broker sets the two side by side.
Can I get a loan after a director penalty notice or a garnishee?
Some lenders still help, others won’t, so it narrows the options and the broker needs to know up front. We don’t negotiate with the ATO or give tax advice: your accountant or tax agent can advise on the notice itself.
What do lenders look for?
An active ABN trading for at least six months (many want a year or more), steady turnover (usually $10,000 a month or more), recent business bank statements, and your ATO statement of account showing the debt. Owning property opens secured options at lower rates.
Will this affect my credit score?
No. Your answers only decide which broker should call you. A credit enquiry happens only when you choose to apply with a lender.
Are you part of the ATO?
No. Your Finance Guide is not affiliated with the ATO. The ATO’s own help with paying, including payment plans, is at ato.gov.au.
How does Your Finance Guide make money?
Licensed brokers who meet our criteria pay Your Finance Guide a partnership fee to receive enquiries from this site. The fee is paid by the broker, not by you, and is not added to your loan. You never pay us. Brokers are usually also paid a commission by the lender if a loan goes ahead, so ask the broker you speak with how they are paid. Full details are in our Credit Guide.
Compare a loan with the ATO’s interest charge
Start now