Check your asset finance options in 60 seconds
Takes about 60 seconds. No credit check at this step.

Every finance broker here is YFG Approved. Our founder, Andy McMaster, spends over two hours with each one, and we check their references, reviews and licence before they hear from you. How we vet
Buying a ute, a truck, machinery or equipment for the business? Your Finance Guide helps Australian business owners quickly check what asset finance options may be available, without the usual bank delays or paperwork upfront.
No credit check to start · Free · No obligation
What are you financing?
Pick the closest match.
Brokers earn the YFG approval. They can lose it.
A licence is the minimum, not the standard. Before a broker hears from a single borrower they pass six checks, and they have to keep passing them. It takes us hours per broker, and it’s meant to.
Paying us doesn’t buy approval. A broker who fails a check doesn’t get enquiries at any price.
The YFG Approved standard: six checks
Two hours with the founder
Andy spends over two hours with every broker: how they work, how they write loans and how they look after people. If they can’t show they know their profession, it ends there.
References checked
We speak to people who have worked with them, so we hear how they operate when nobody is selling.
Reviews read
We read what their clients say about them in public, the hard reviews as well as the good ones.
Licence and accreditations
Their Australian Credit Licence or credit representative number, looked up on ASIC’s register, membership of AFCA (the free complaints scheme) and their accreditations.
Held to our rules
Your enquiry goes to them alone, not to a list, and they call within one business day, already knowing your answers.
Answerable to you
If a broker doesn’t call, doesn’t explain your options or doesn’t treat you well, tell us. We follow up every report, and a broker who falls short loses their YFG approval.
“We check every broker. I spend over two hours with each one to make sure they understand their profession, know how to write loans and get people what they need.”Andy McMaster, founder
Licensed brokers who meet our criteria pay Your Finance Guide a partnership fee to receive enquiries from this site. The fee is paid by the broker, not by you, and is not added to your loan. Read our Credit Guide.
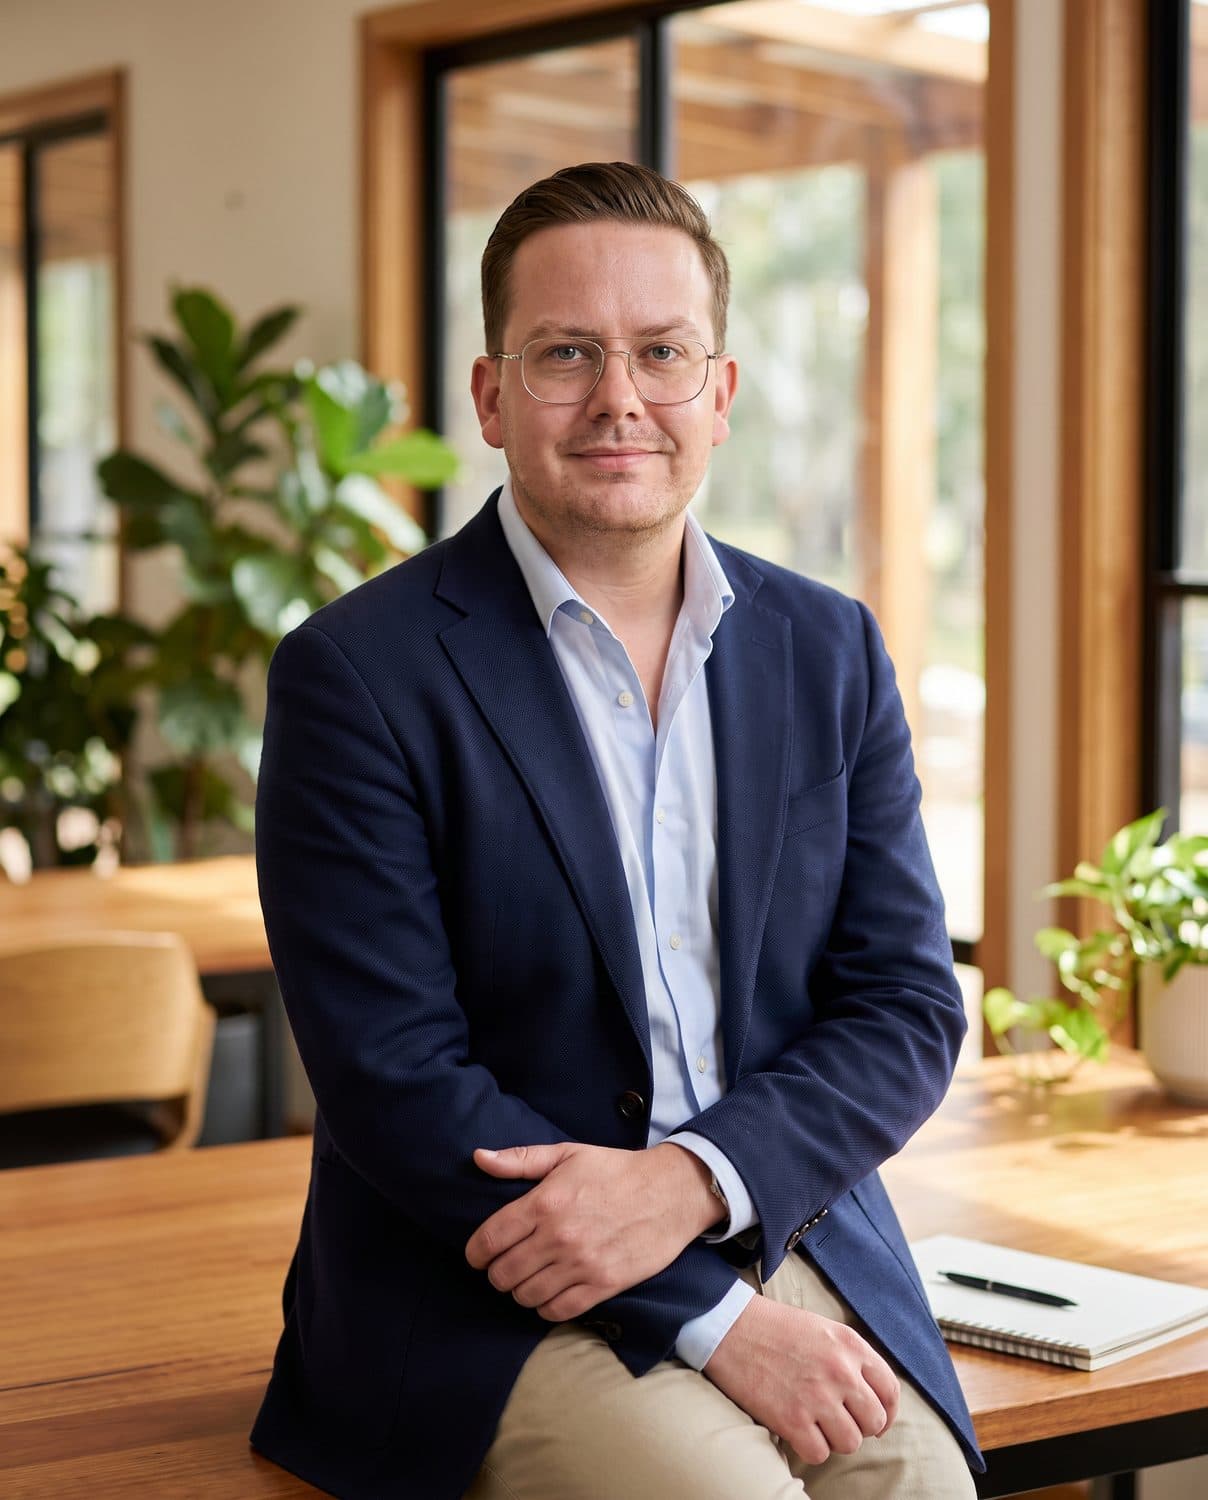
“I got tired of seeing people get ripped off.”
So I built Your Finance Guide to be the benchmark.
I spent more than a decade in the property industry advising buyers and investors, and I got tired of seeing people get ripped off. So every broker here has sat with me for over two hours, and we have checked their references, reviews and accreditations, before they hear from you.
Andy McMasterFounder, Your Finance Guide · Why I built itYour broker compares lenders like...

Lenders your broker can compare include Prospa, Moula, OnDeck, Judo Bank, Angle Finance, Latitude, Capify, Earlypay, Plenti, Liberty, Macquarie, Westpac, ANZ.
Examples of lenders on the partner broker’s panel. Which ones are open to you depends on your circumstances, and no lender can be promised.
How it works
Step 1: Answer a few quick questions
About 60 seconds. Pick the asset, pick your business and the register fills in the ABN and GST dates.
Step 2: Get connected with a broker
A licensed broker who works your kind of lending calls within one business day, already knowing your answers.
Step 3: Get options tailored to your business
Lenders tailor rates, terms and structure to your business, and the broker gives you your actual rate.
We don’t lend, and we don’t sell finance.
Your Finance Guide is a finance education publisher. We are not a lender, a broker or a credit provider. This check exists because the first thing most owners hear from a lender is a decline, after a hard credit enquiry, when a five-minute read of policy would have pointed them at the right lender to begin with.
So the check costs nothing and takes about a minute. Then we connect you with a licensed broker who works your kind of lending. They call within one business day, already knowing your answers, so the conversation starts at the right lender instead of at square one.
Frequently asked questions
What is asset finance?
A loan where the thing you are buying is the security. Because the lender can take the asset back, it prices lower than an unsecured business loan and is written faster, often from your ABN history, credit file and the quote alone. The business uses the asset from day one and pays it off over two to seven years.
What can you buy with asset finance?
Cars, utes and vans, trucks and trailers, excavators and earthmoving plant, manufacturing and workshop machinery, agricultural equipment, forklifts, medical and dental equipment, fit-outs, IT hardware and solar. New or used, from a dealer, an auction or a private seller, and you can refinance an asset you already own to release cash.
What are the different types of asset finance?
This service is for loans, not leases. A chattel mortgage is the most common for businesses: the business owns the asset from day one, and if it is registered for GST, the GST in the price may be claimable on the next BAS (check with your accountant). A commercial hire purchase transfers ownership once the last payment is made. The broker matches the structure to your business and how long you will keep the asset.
Am I eligible to apply for asset finance?
Most low-doc products want an ABN active for two years, GST registration, a clean credit file and either property ownership or a deposit of 10 to 20 per cent. Newer businesses, used or older assets and imperfect credit are still fundable, usually with a deposit, a shorter term or a specialist lender. The check gives the broker exactly these facts.
What documents do I need to apply?
For a low-doc approval under about $150,000 to $250,000, usually photo ID, your ABN and GST details, and the quote or invoice for the asset. Larger amounts, a private sale or a newer ABN add bank statements, financials or a valuation. Private sales also need an inspection and a PPSR check for finance owing.
Can I refinance my existing asset finance?
Yes. Refinancing to a lower rate, extending the term to ease cash flow, consolidating several loans, or refinancing an asset you own outright to release cash are all common. Tell the broker what you have now and they will set the cost of switching against the saving.
How quickly can I get asset finance approved?
It depends on the lender, the asset and your documents, and nobody can promise a time before a lender has assessed the application. A low-doc application on a standard asset is usually quicker than an older asset, a private sale or a full-doc file. The broker calls within one business day of your check, already knowing your answers, so the clock starts sooner.
Is this a credit check?
Not at this step. Your answers only decide which broker should call you, and no credit enquiry happens unless you authorise a specific lender application.
How does Your Finance Guide make money?
Licensed brokers who meet our criteria pay Your Finance Guide a partnership fee to receive enquiries from this site. The fee is paid by the broker, not by you, and is not added to your loan. You never pay us. Brokers are usually also paid a commission by the lender when a loan settles, so ask the broker you speak with how they are paid. Full details are in our Credit Guide.